


Recently, Cedar Street Research released a bear case breakdown / short take on Uber’s insurance reserves.
The core argument is that Uber is essentially operating as a unregulated, under-capitalized insurance company and that its Free Cash Flow is “mirage” propped up by insurance float and SBC.
Yes, there are some valid points in the take, specifically regarding a lack of transparency, however I feel they are missing the forest for the trees.
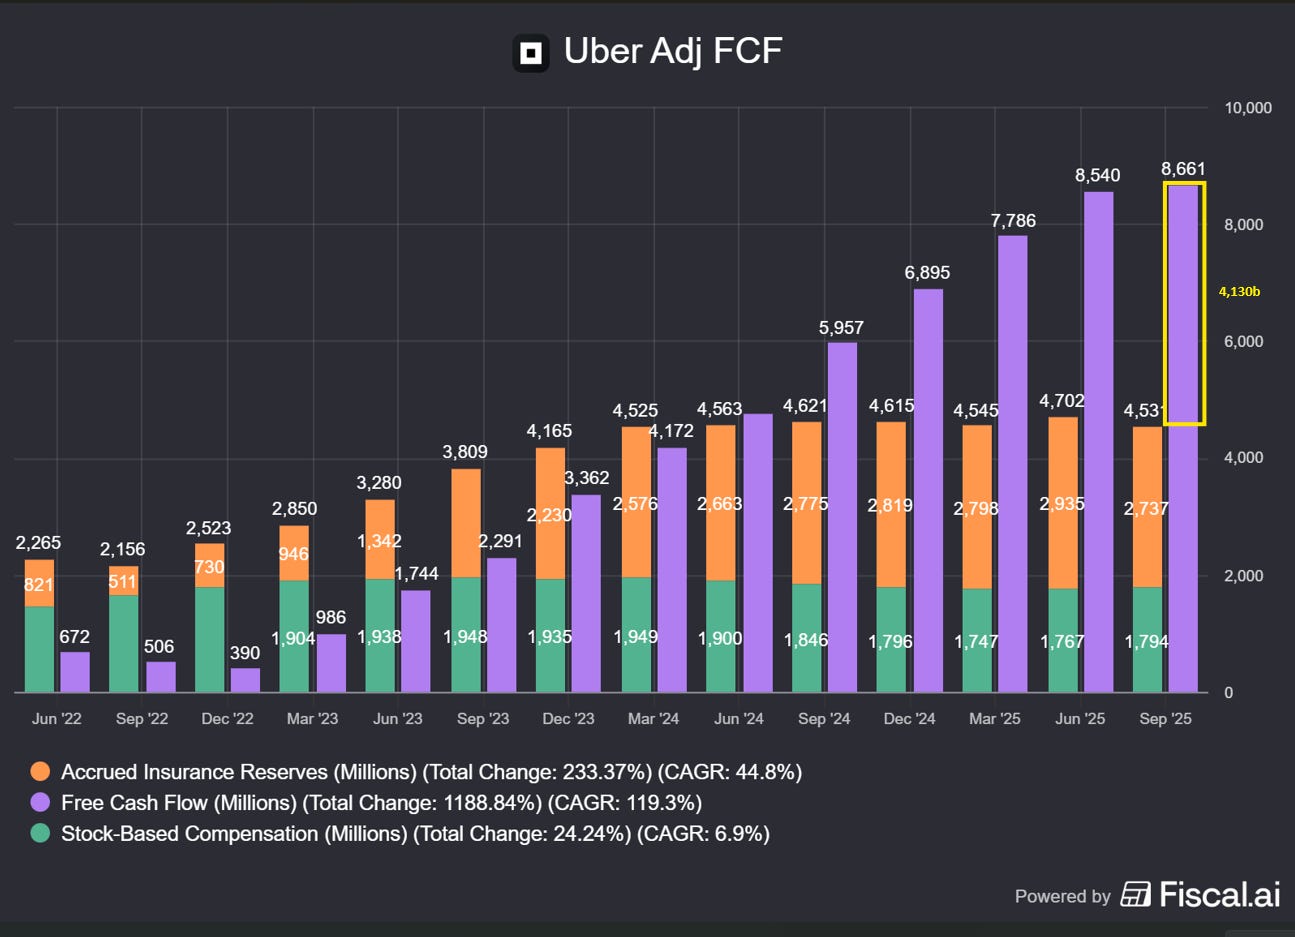
Regarding Free Cash Flow: I agree. To get an accurate picture on Uber’s Free Cash Flow or Owner’s Earnings, we should remove the Stock Based Comp and Accrued Insurance Reserve add ins.
SBC is an real dilutive expense and Accrued Insurance Reserves should be considered restricted cash for future payouts that is not available to shareholders.
Adjusting for this brings Uber’s true, organic FCF from 8.6b to 4.13b.
The thing is, this isn’t a mirage. I am well aware of the FCF multiple I am paying for Uber, as are many of its well-known investors. The realit…
